
Choosing the right umbrella insurance carrier in Massachusetts depends on your specific risk profile, underlying liability limits, and industry requirements. Click Insurance helps small business owners navigate these options by comparing multiple independent carriers to find coverage that aligns with your operational needs and budget. Because we are an independent agency, we are not tied to a single insurer, allowing us to present a variety of policy structures that fit your unique business context.
Understanding Commercial Umbrella Policies
Commercial umbrella insurance is a type of liability coverage that provides additional protection above the limits of your underlying primary policies, such as general liability or commercial auto. This excess coverage kicks in when a claim exceeds your primary policy limits but falls below the umbrella limit. For small business owners in Massachusetts, this layer of protection is critical because a single severe incident can result in legal costs and settlements that far exceed standard primary coverage.
The primary function of an umbrella policy is to bridge the gap between your primary limits and your total asset exposure. If you do not have sufficient underlying coverage, an umbrella policy may not attach correctly, leaving you exposed. Therefore, the first step in selecting a carrier is ensuring your primary policies meet the minimum attachment requirements of the umbrella insurer. This structural alignment is a key factor in determining which carrier offers the most suitable coverage for your specific situation.
Key Factors in Carrier Selection
When evaluating Massachusetts umbrella insurance carriers, small business owners should look beyond the premium price to assess the carrier's financial strength and policy terms. Financial stability is paramount because the carrier must be able to pay large claims when they occur. You should review the carrier's financial ratings from recognized agencies to ensure they have the capacity to handle significant liability events.
Policy terms, including exclusions and conditions, vary significantly between carriers. Some carriers may exclude certain high-risk activities or industries, while others may offer broader coverage for specific sectors like construction or professional services. It is essential to read the policy language carefully to understand what is covered and what is excluded. An independent agency can help you interpret these terms and identify potential gaps in your coverage.
Industry-Specific Coverage Considerations
Different industries face distinct risk profiles, which influences the type of umbrella coverage they need. For example, a construction firm in Massachusetts may face higher risks of bodily injury and property damage, requiring robust underlying general liability and auto coverage. A professional services firm, such as a law or accounting practice, may need to consider how their umbrella policy interacts with their professional liability or errors and omissions coverage.
Some carriers specialize in certain industries and may offer more tailored coverage options for those sectors. For instance, a carrier with experience in insuring healthcare providers may have specific endorsements or exclusions that differ from a carrier focused on manufacturing. Understanding your industry's specific risks helps you identify carriers that have the expertise and policy forms to address those risks effectively. This alignment ensures that your umbrella policy complements your primary coverage rather than creating conflicts or gaps.
The Role of an Independent Agency
Working with an independent insurance agency like Click Insurance offers distinct advantages when selecting an umbrella carrier. Independent agencies represent multiple insurance companies, giving you access to a wider range of policy options. This breadth allows us to compare different carriers' terms, limits, and pricing to find the best fit for your business. We act as your advocate, helping you navigate the complexities of excess liability coverage.
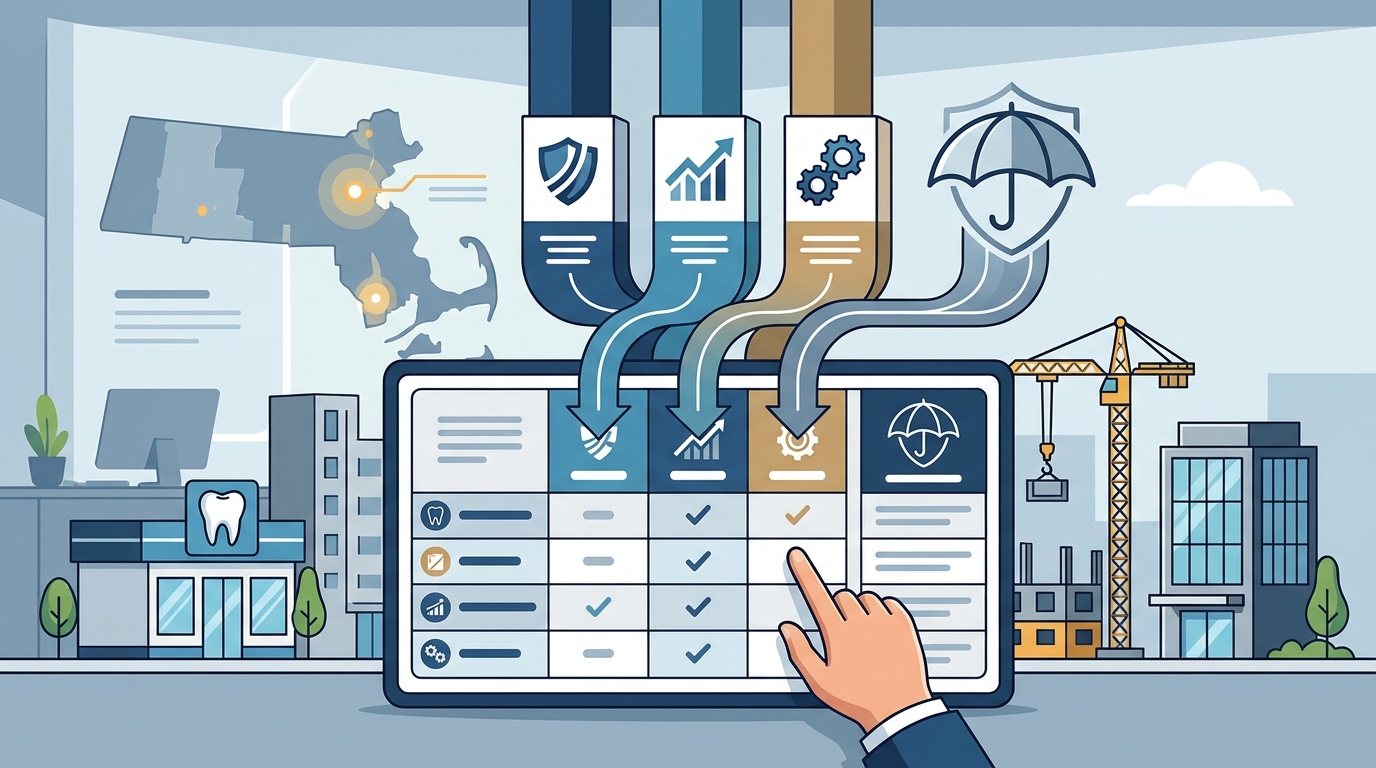
Reviewing Your Coverage Needs
Before finalizing a carrier choice, it is important to conduct a thorough review of your current insurance portfolio. This includes assessing your primary liability limits, your total asset value, and any contractual requirements from clients or partners. Some contracts may require specific umbrella limits or specific carrier approvals. Ensuring that your chosen carrier meets these requirements is crucial for maintaining your business relationships and compliance.
Regularly reviewing your coverage is also important as your business grows. Changes in revenue, employee count, or operational scope can impact your risk profile and, consequently, your insurance needs. An annual policy review with your agency can help you adjust your limits and coverage types to reflect your current business reality. This proactive approach helps you maintain adequate protection without overpaying for unnecessary coverage.
Key Takeaways
- Commercial umbrella insurance provides excess liability coverage above your primary policy limits.
- Financial strength and policy terms are more important than premium price when selecting a carrier.
- Ensure your primary policies meet the minimum attachment requirements of the umbrella carrier.
- Industry-specific risks should influence your choice of carrier and policy endorsements.
- Independent agencies like Click Insurance can compare multiple carriers to find the best fit.
- Regularly review your coverage to ensure it aligns with your growing business needs.
Frequently Asked Questions
What is the difference between personal and commercial umbrella insurance?
Personal umbrella insurance covers personal liability risks, such as auto accidents or home injuries, while commercial umbrella insurance covers business liability risks. They are separate policies and cannot be combined into a single policy.
Do I need an umbrella policy if I have high primary limits?
Even with high primary limits, an umbrella policy can provide additional protection against catastrophic claims. The need depends on your total asset exposure and risk profile.
Can I buy an umbrella policy without primary liability insurance?
No, umbrella policies require underlying primary liability coverage. The umbrella policy attaches only after the primary limits are exhausted.
How much umbrella coverage should a small business have?
The amount of coverage depends on your assets, industry risks, and contractual requirements. Consulting with an insurance professional can help determine the appropriate limit.
Does umbrella insurance cover professional liability?
Umbrella policies typically do not cover professional liability or errors and omissions claims. You need a separate professional liability policy for those risks.
How does an independent agency help with carrier selection?
An independent agency represents multiple carriers, allowing you to compare different policy terms, limits, and pricing to find the best fit for your business.
Next Steps for Your Business
Selecting the right umbrella insurance carrier is a critical decision for protecting your business assets. By understanding the key factors in carrier selection and leveraging the expertise of an independent agency, you can make an informed choice that aligns with your specific needs. Contact Click Insurance to discuss your coverage options and find a policy that fits your business profile.