
Umbrella insurance is a liability policy that provides additional coverage above the limits of your underlying insurance policies. To know if your underlying coverage meets the requirements for umbrella protection, you must verify that your primary policies (such as auto and homeowners) meet specific minimum limits, are issued by approved carriers, and contain no exclusions that would void the excess coverage. Click Insurance helps clients navigate these technical requirements to ensure their liability protection is seamless and compliant.
Understanding the Role of Underlying Policies
Umbrella insurance is not a standalone solution for all liability risks; it is an excess layer that sits on top of primary coverage. The primary policies, such as auto and homeowners insurance, are the first to respond to a claim. If the damages exceed the limits of these primary policies, the umbrella policy steps in to cover the additional costs, up to its own limit. This structure means that the integrity of your umbrella protection is directly tied to the quality and limits of your underlying policies.
For business owners, this concept is equally critical. Commercial general liability and professional liability policies often serve as the underlying layers for commercial umbrella coverage. If a business operates in high-risk sectors like construction or healthcare, the primary policies must be robust enough to satisfy the umbrella carrier's underwriting standards. Click Insurance works with multiple carriers to ensure that the primary and excess layers are aligned, preventing gaps in coverage that could leave a client exposed to significant financial liability.
Minimum Limits and Carrier Approval
Carrier approval is another critical factor. Not all insurance companies are approved to serve as underlying carriers for every umbrella policy. Some umbrella carriers maintain a list of preferred or approved primary insurers. If your current auto or homeowners policy is issued by a carrier that is not on the approved list, you may need to switch carriers or seek a specific waiver. Click Insurance helps clients identify which carriers are approved for their specific umbrella needs, ensuring that the underlying policies are recognized by the excess insurer.
Exclusions and Policy Terms
Beyond limits and carrier approval, the specific terms and exclusions of your underlying policies play a vital role in umbrella eligibility. Umbrella carriers review the primary policies to ensure there are no exclusions that would create a gap in coverage. For instance, if your homeowners policy excludes liability for certain activities, the umbrella policy may also exclude those activities. This alignment is essential to ensure that the umbrella policy provides the intended protection.
For businesses, this review is even more detailed. Commercial policies often contain specific exclusions for professional services, cyber incidents, or environmental damage. If a business relies on a commercial umbrella to cover these risks, the underlying policies must be structured to support that coverage. Click Insurance reviews the policy terms of both the primary and excess layers to identify potential gaps. This proactive approach helps clients avoid surprises during a claim, ensuring that their coverage is as comprehensive as possible.
Business-Specific Underlying Requirements
For business owners, the underlying requirements for commercial umbrella insurance are more complex than for personal policies. Commercial umbrella policies often require specific underlying limits for general liability, professional liability, and auto liability. The exact requirements depend on the industry and the risk profile of the business. For example, a construction company may need higher general liability limits than a consulting firm to satisfy the umbrella carrier's requirements.
Additionally, commercial umbrella policies may require that the underlying policies are issued by carriers with a certain financial strength rating. This ensures that the primary insurer is financially stable enough to pay out on large claims. Click Insurance helps business owners assess their risk profile and determine the appropriate underlying limits and carriers. This ensures that their commercial umbrella policy is properly structured to provide the protection they need.
How to Verify Your Coverage
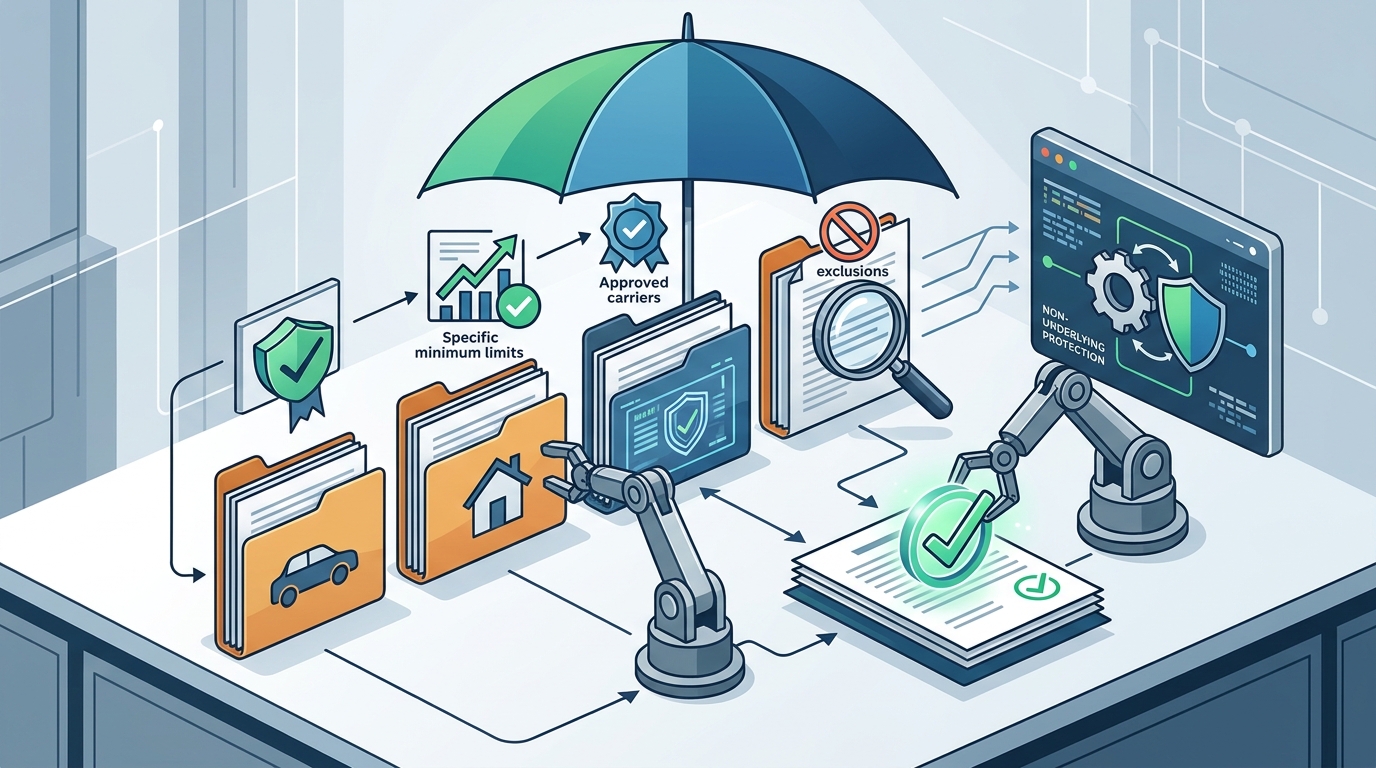
Verifying that your underlying coverage meets the requirements for umbrella protection is a multi-step process. First, review your current auto and homeowners policies to check your liability limits. Next, confirm that your carriers are approved by your umbrella insurer. Finally, review the policy terms to ensure there are no exclusions that would create a gap in coverage. This process can be complex, especially for businesses with multiple policies and high-risk operations.
Click Insurance simplifies this process by providing a comprehensive review of your insurance portfolio. Our team works with you to identify any gaps or mismatches between your primary and excess policies. We help you adjust your underlying limits, switch carriers if necessary, and review policy terms to ensure that your umbrella protection is seamless. This proactive approach helps you avoid coverage gaps and ensures that you are protected against large liability claims.
Key Takeaways
- Umbrella insurance is an excess layer that requires underlying policies to meet specific minimum limits.
- Carrier approval is essential; not all primary insurers are approved for every umbrella policy.
- Exclusions in underlying policies can create gaps in umbrella coverage, so policy terms must be reviewed.
- Businesses have more complex underlying requirements, including specific limits for general and professional liability.
- Click Insurance helps clients verify that their underlying coverage meets umbrella requirements, ensuring seamless protection.
Frequently Asked Questions
What are the minimum limits for underlying auto insurance for a personal umbrella policy?
Do I need to switch my auto insurance carrier to get umbrella coverage?
Not necessarily, but your current carrier must be approved by your umbrella insurer. If your carrier is not on the approved list, you may need to switch or seek a waiver.
How does Click Insurance help with verifying underlying coverage?
Click Insurance reviews your current policies to ensure they meet the minimum limits, carrier approval, and policy term requirements for your umbrella policy. We help identify and fix any gaps in coverage.
Are commercial umbrella requirements different from personal umbrella requirements?
Yes, commercial umbrella policies often have more complex requirements, including specific limits for general liability, professional liability, and auto liability, as well as financial strength ratings for the underlying carriers.
What happens if my underlying policy has an exclusion?
If your underlying policy has an exclusion, the umbrella policy may also exclude that risk. This can create a gap in coverage, so it is important to review policy terms carefully.
Conclusion
Ensuring that your underlying coverage meets the requirements for umbrella protection is a critical step in securing comprehensive liability protection. By verifying minimum limits, carrier approval, and policy terms, you can avoid gaps in coverage and ensure that your umbrella policy works as intended. Click Insurance is here to help you navigate this process, providing the expertise and guidance you need to protect your assets and business. To discuss your coverage needs, .